The Psychology of Wealth: 7 Habits That Keep People Poor
Wealth mindset and financial freedom concept
INTRODUCTION
Wealth is not just about money. It is about mindset, habits, and the daily choices that compound over time. The difference between those who build lasting wealth and those who struggle financially often comes down to psychology—not income. While many people believe that wealth is determined by how much money you earn, the evidence suggests otherwise. Countless studies have shown that individuals who receive sudden windfalls—lottery winnings, inheritances, or large settlements—often end up worse off financially within a few years. This phenomenon, known as the “lottery curse,” reveals a profound truth: money does not fix poor financial habits. It amplifies them.
Consider this staggering statistic: nearly 70 percent of lottery winners go bankrupt within a few years of their win. Professional athletes, who earn millions of dollars during their careers, are 60 percent more likely to file for bankruptcy within five years of retirement than the general population. These numbers are not anomalies—they are evidence of a deeper pattern. The problem is not the amount of money coming in. The problem is the habits, beliefs, and behaviors that govern how that money is managed.
The wealthy think differently. They act differently. And most importantly, they have developed habits that systematically build wealth over time. These habits are not innate talents or genetic gifts. They are learned behaviors that anyone can cultivate with intention and effort. Conversely, the habits that keep people poor are often invisible to those who practice them. They are automatic, comfortable, and deeply ingrained. They are the product of upbringing, environment, and the subtle messages we absorb about money from a young age.
This article explores the seven most destructive financial habits that keep people trapped in poverty or financial mediocrity. More importantly, it provides actionable strategies to break these patterns and build lasting wealth. Understanding these habits is the first step toward transformation. Implementing the solutions is the second. The journey to financial freedom begins with awareness—and the willingness to change.
Spending habits and consumer behavior
1. Living Beyond Your Means
The first and most destructive habit is spending more than you earn. It sounds simple, yet millions of people practice it daily. They finance cars they cannot afford, buy homes with payments that stretch their budgets to the breaking point, and use credit cards to fund lifestyles that exceed their incomes. The mathematics of this habit are unforgiving: when you spend more than you earn, you accumulate debt. When you accumulate debt, you pay interest. When you pay interest, you lose the opportunity to invest and grow your wealth. It is a cycle that perpetuates itself.
The Psychology: Living beyond your means is often driven by social comparison. We compare ourselves to neighbors, colleagues, and social media influencers. We see their homes, cars, and vacations and feel inadequate. To close the gap, we spend money we do not have. This is not a rational decision—it is an emotional one. The desire to appear successful or keep up with peers creates a powerful psychological pressure to spend. Advertisers and marketers understand this dynamic perfectly and exploit it relentlessly. They sell not products, but identities, status, and belonging.
The Reality: Wealth is not built by appearing wealthy. It is built by saving and investing the difference between what you earn and what you spend. The person driving a luxury car may be drowning in debt, while the person driving a modest vehicle may be quietly building a fortune. The wealthy understand that true financial freedom comes not from consumption but from accumulation. They know that every dollar spent on something that does not appreciate in value is a dollar that cannot work for them in the future.
The Solution: Live below your means. Spend less than you earn. This is the single most important habit of wealth building. Track every expense for 30 days. Identify areas where you can cut back. Automate savings before you see your paycheck. Create a budget that aligns with your long-term goals. The goal is not to live a life of deprivation but to align your spending with your values. Spend on things that truly matter to you and cut ruthlessly on everything else. This requires discipline, but the rewards are immense.
Financial education and learning concept
2. Neglecting Financial Education
The wealthy invest in financial education. The poor avoid it. This is not an accident—it is a choice. The wealthy understand that financial literacy is the foundation upon which all wealth is built. They read books, attend seminars, listen to podcasts, and seek out mentors. They are constantly learning about money, investing, taxes, and economics. The poor, by contrast, often view financial education as boring, intimidating, or unnecessary. They convince themselves that they are “not good with money” and avoid the topic entirely.
The Psychology: Financial concepts can be intimidating. Terms like compound interest, asset allocation, and tax efficiency sound complex. Many people convince themselves they are “not good with money” and avoid learning. This avoidance becomes a self-fulfilling prophecy. The less you know, the more vulnerable you are to financial mistakes. The more mistakes you make, the more you reinforce the belief that you are not good with money. It is a vicious cycle that keeps people trapped.
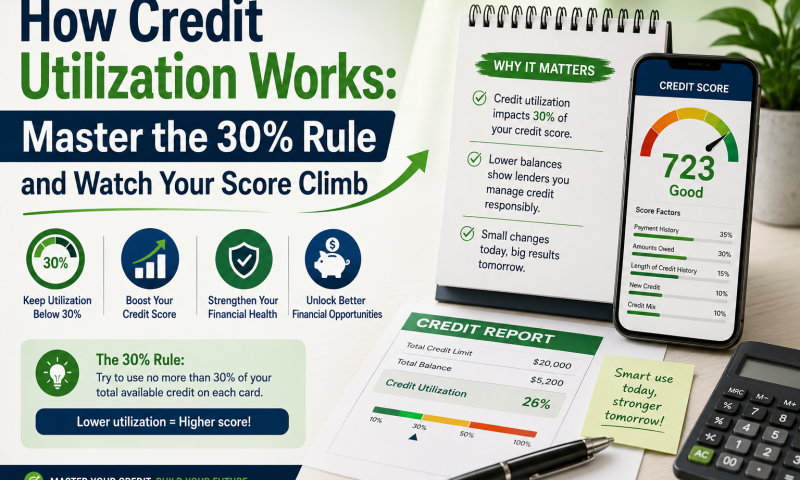
The Reality: Financial literacy is not optional. It is essential. Without understanding how money works, you are at the mercy of financial institutions, predatory lenders, and your own ignorance. The wealthy understand compound interest, tax advantages, and the difference between assets and liabilities. They know how to read financial statements, evaluate investments, and plan for retirement. They have made financial education a priority because they understand that knowledge is power—and that the financial system is designed to benefit those who understand it.
The Solution: Commit to lifelong financial education. Read books on personal finance and investing. Listen to podcasts. Take courses. Follow financial experts. Understand how taxes work, how to invest, and how to build wealth systematically. Financial education is not about becoming an expert—it is about becoming competent. You do not need to understand every investment vehicle. You need to understand the fundamentals that drive wealth building. Start with the basics and build from there. Every hour you invest in financial education will pay dividends for the rest of your life.
Goal setting and financial planning
3. Failing to Set Financial Goals
The wealthy set specific financial goals. The poor drift through life without a clear financial destination. The wealthy know exactly what they want to achieve and when they want to achieve it. They have written goals, detailed plans, and regular review processes. The poor, by contrast, have vague aspirations at best. They hope to be “rich someday” or “financially comfortable,” but they have no concrete definition of what that means or how they will get there.
The Psychology: Without goals, there is no direction. Money comes in, money goes out, and there is no intentionality about where it goes. The lack of goals creates a sense of powerlessness—financial outcomes feel random and uncontrollable. This sense of powerlessness reinforces inaction. If you do not believe you can change your financial situation, you will not try. And if you do not try, your situation will not change.
The Reality: Goals provide direction, motivation, and a framework for decision-making. When you have a clear goal—buying a home, retiring early, starting a business—every financial decision becomes clearer. You ask: “Will this move me closer to my goal or further away?” This clarity transforms financial decision-making from a series of arbitrary choices into a coherent strategy. It helps you say no to things that do not matter and yes to things that do.
The Solution: Set specific, measurable financial goals. Write them down. Break them into smaller milestones. Review them regularly. Your goals should be ambitious but achievable. Create a timeline for each goal. Share them with an accountability partner. Visualize your goals regularly. The more concrete and vivid your goals are, the more motivated you will be to achieve them. Goals are the compass that guides your financial journey. Without them, you are wandering. With them, you are navigating purposefully.
Wealth building and investment concept
4. Avoiding Risk and Investing
The wealthy invest. The poor keep their money in cash, losing purchasing power to inflation every single year. The wealthy understand that cash is not a safe investment—it is a guaranteed loss. Inflation erodes the purchasing power of cash at an average rate of 3 percent per year. Over 20 years, the value of cash is cut nearly in half. The wealthy invest their money in assets that grow faster than inflation—stocks, real estate, businesses, and other productive assets.
The Psychology: Risk aversion is natural. Fear of losing money is one of the most powerful human emotions. But avoiding risk entirely is the riskiest strategy of all. Inflation erodes cash value steadily and silently. You do not feel the loss because it happens gradually, but it is just as real as losing money in the stock market. The wealthy understand this. They accept the volatility of investing because they know that the alternative—guaranteed loss—is worse.
The Reality: Wealth is not built by saving alone—it is built by investing. The average return of the stock market over the past century is about 10 percent annually. Money in a savings account earns less than 1 percent. Over 30 years, $100,000 invested at 10 percent grows to $1.7 million. The same money in a savings account grows to just $134,000. This is the power of compound interest. It is the eighth wonder of the world, as Albert Einstein famously said. But it only works if you invest.
The Solution: Start investing as early as possible. Even small amounts compound significantly over time. Educate yourself on basic investing principles. Start with low-cost index funds or ETFs. Diversify your investments. Think long term and do not panic during market downturns. The greatest risk in investing is not losing money—it is not investing at all. Inflation is guaranteed. Market returns are not, but historically they have far outpaced inflation. Invest consistently, stay disciplined, and let time do its work.
Financial discipline and taking action
5. Procrastinating on Financial Action
The wealthy take action. The poor wait for the “right time” to start. The wealthy understand that time is their greatest asset. They start saving and investing early, even if the amounts are small. They do not wait for the perfect opportunity or the ideal market conditions. The poor, by contrast, are always waiting. They wait until they have more money. They wait until they know more. They wait until they feel ready. And while they wait, time passes and opportunities are lost.
The Psychology: Procrastination is comfortable. It feels safer to delay decisions, especially financial ones. But waiting has a hidden cost: the cost of missed opportunity. Compound interest is powerful, but it requires time to work. The earlier you start, the more time your money has to grow. The wealthy understand this intuitively. They know that the best time to start was yesterday. The second best time is today.
The Reality: The earlier you start saving and investing, the less you need to save overall. A person who starts investing $500 per month at age 25 will have more money at retirement than someone who starts at age 35 investing $1,000 per month. Procrastination costs you time, and time is money. Every day you delay is a day of lost compound growth. The difference between starting now and starting later can be hundreds of thousands of dollars over a lifetime.
The Solution: Start now. Do not wait for the perfect time. Do not wait until you make more money. Do not wait until you feel ready. Start with whatever you have. Small actions compound over time. The best time to start building wealth was 10 years ago. The second best time is today. Every day you delay is a day of lost compound growth. Take action today, no matter how small. The journey of a thousand miles begins with a single step.
Social influence and wealth mindset
6. Surrounding Yourself with the Wrong People
The wealthy surround themselves with ambitious, success-oriented people. The poor surround themselves with those who reinforce limiting beliefs. The wealthy understand that they are the average of the five people they spend the most time with. They choose their social circle carefully, seeking out people who challenge them, inspire them, and hold them accountable. The poor, by contrast, often surround themselves with people who reinforce their existing beliefs and behaviors.
The Psychology: We are the average of the five people we spend the most time with. If those people have negative attitudes toward money, complain about their circumstances, and lack ambition, those attitudes will become yours. Social influence is subtle but powerful. The people around you shape your beliefs, habits, and expectations. If you surround yourself with people who are building wealth and pursuing ambitious goals, you will naturally adopt similar behaviors. If you surround yourself with people who are struggling financially and blaming external factors, you will likely follow a similar path.
The Reality: Social influence is powerful. The people around you shape your beliefs, habits, and expectations. If you surround yourself with people who are building wealth and pursuing ambitious goals, you will naturally adopt similar behaviors. If you surround yourself with people who are struggling financially and blaming external factors, you will likely follow a similar path. The wealthy understand this and are intentional about their social circles. They join mastermind groups, attend networking events, and cultivate relationships with people who are where they want to be.
The Solution: Build a network of ambitious, success-oriented people. Join professional organizations. Attend networking events. Find mentors. Seek out people who have achieved what you want to achieve. Limit time with people who reinforce limiting beliefs. You cannot change who you are surrounded by overnight, but you can intentionally invest time in relationships that support your growth. Be selective about who you allow into your inner circle. Your network is your net worth.
Value creation and generosity
7. Failing to Give and Create Value
The wealthy focus on creating value for others. The poor focus on getting value for themselves. The wealthy understand that wealth is a byproduct of value creation. They focus on solving problems, meeting needs, and serving others. The poor, by contrast, often approach money from a scarcity mindset, focusing on what they can get rather than what they can give.
The Psychology: Many people approach money from a scarcity mindset: there is only so much to go around. This leads to a focus on taking rather than creating. But wealth is not a zero-sum game. It is created through value. The person who focuses solely on getting—getting a raise, getting a deal, getting an advantage—often misses the opportunity to create lasting value. The wealthy understand that the more value they create for others, the more wealth they will generate for themselves.
The Reality: The most successful people in history are those who created enormous value for others. They solved problems, met needs, and provided solutions. In doing so, they generated wealth for themselves. The person who focuses solely on getting—getting a raise, getting a deal, getting an advantage—often misses the opportunity to create lasting value. The wealthy understand that generosity is not just a moral virtue—it is a wealth-building strategy. When you give, you attract. When you serve, you build reputation and trust. When you create value, money follows.
The Solution: Shift from a scarcity mindset to an abundance mindset. Focus on how you can create value for others. How can you solve a problem? How can you make someone’s life better? How can you provide a service that people need? When you create value, money follows. Wealth is not something you take. It is something you earn by creating value for others. The more value you create, the more wealth you can generate. Start today. Find one way to create value for someone else. The returns will compound.
Wealth building action plan
The Action Plan: Break the Habits, Build the Wealth
📋 Your 30-Day Action Plan
Week 1: Awareness
Track every expense for 7 days. Record everything. Identify where you are living beyond your means. Assess your financial education gaps. Write down your long-term financial goals. This week is about understanding your current reality. You cannot change what you do not measure.
Week 2: Action
Create a realistic budget based on your tracking. Set up automatic savings transfers. Read one book on personal finance. Identify one investment vehicle to research. This week is about taking action. Small steps compound over time. Start with one change and build from there.
Week 3: Environment
Evaluate the people you surround yourself with. Join one professional or networking group. Find a mentor or accountability partner. Remove negative financial influences. This week is about your environment. The people you surround yourself with shape your habits and beliefs.
Week 4: Commitment
Review and refine your goals. Develop a long-term investment strategy. Identify ways to create more value for others. Commit to ongoing financial education. This week is about commitment. Lasting change requires ongoing effort. Build systems that support your new habits.
Conclusion
Wealth is not about luck. It is not about inheritance. It is not about who you know. Wealth is about habits—the daily, consistent actions that compound over time. The seven habits outlined in this article are destructive, but they are not permanent. They can be broken. With awareness, intention, and consistent effort, you can replace them with habits that build lasting wealth.
The journey to financial freedom is not easy, but it is simple. Spend less than you earn. Invest the difference. Educate yourself. Set goals. Take action. Surround yourself with positive influences. Create value for others. These are not complicated concepts, but they require discipline and persistence.
The choice is yours. You can continue with the habits that keep you poor, or you can develop the habits that build wealth. The path to wealth starts with a single decision: to change. Today is the day you make that decision. Your financial transformation begins now.