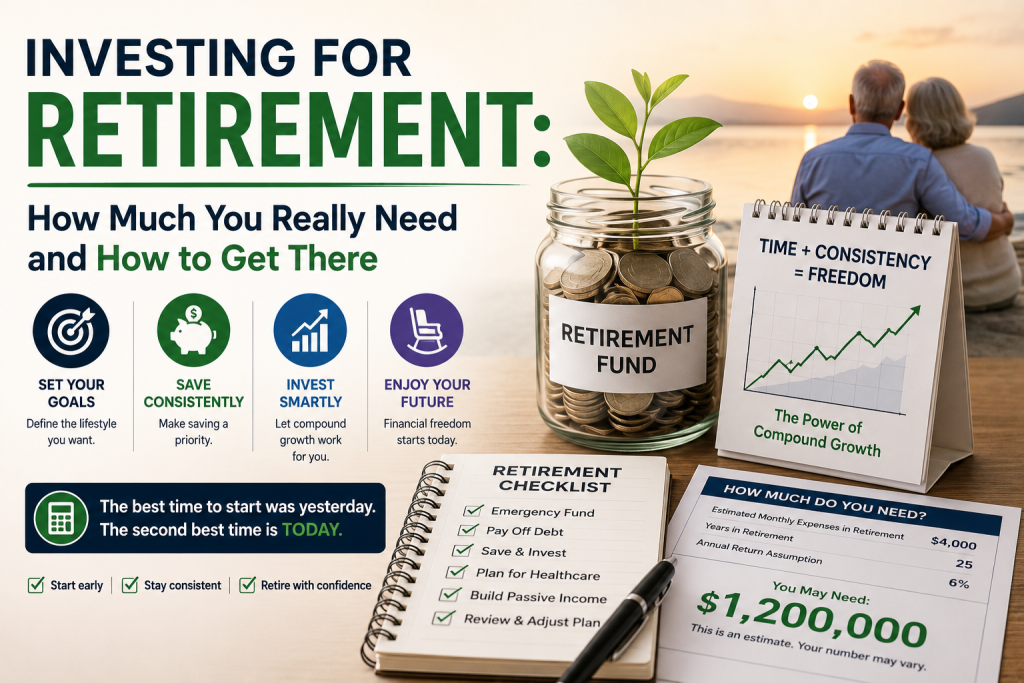
Investing for Retirement: How Much You Really Need and How to Get There
INTRODUCTION
Retirement planning can feel overwhelming. How much do you really need? When should you start? What if you are behind? These are common questions that keep people up at night. The good news is that retirement planning is not as complicated as it seems. With a clear understanding of your goals, a realistic savings plan, and consistent action, you can build a comfortable retirement.
This guide provides a comprehensive overview of retirement planning. It covers how much you need, how to calculate your retirement number, strategies to reach your goal, and what to do if you are behind. Whether you are just starting your career or nearing retirement, these insights can help you plan for a secure financial future.
THE RETIREMENT CRISIS: WHY YOU NEED TO PLAN
The traditional retirement model is changing. Pensions are increasingly rare. Social Security faces funding challenges and may not provide the same level of benefits in the future. People are living longer, which means retirement savings need to last longer. The average retirement now lasts 20 to 30 years or more. Without careful planning, you risk running out of money in retirement.
The data is sobering. According to recent studies, the average retirement savings for Americans aged 55-64 is approximately $120,000. This is far below what is needed for a comfortable retirement. Many people have not saved enough and are at risk of financial insecurity in their later years. The time to start planning is now.
HOW MUCH DO YOU REALLY NEED?
The amount you need for retirement depends on several factors. Your desired lifestyle in retirement is a key consideration. Will you travel extensively, live modestly, or somewhere in between? Your expected expenses, including housing, healthcare, and daily living costs, matter. Your anticipated lifespan is important—the longer you live, the more you need. Inflation will erode your purchasing power over time, so you need to account for rising costs. Your expected retirement income from sources like Social Security, pensions, and rental properties should be factored in. Your healthcare needs, including long-term care, are also a consideration.
A common rule of thumb is to plan to replace 70% to 80% of your pre-retirement income. This assumes that some expenses, like commuting and payroll taxes, will decrease in retirement. However, healthcare costs often increase. If you earn $100,000 per year before retirement, you might need $70,000 to $80,000 per year in retirement.
THE 4% RULE
The 4% rule is a widely used guideline for retirement planning. It suggests that you can withdraw 4% of your retirement portfolio in the first year of retirement, and then adjust that amount for inflation each subsequent year. The rule is based on historical market data and is designed to help ensure that your savings last for 30 years.
To use the 4% rule, multiply your annual retirement expenses by 25. For example, if you need $50,000 per year in retirement, you would need a portfolio of $1,250,000 ($50,000 x 25 = $1,250,000). If you need $80,000 per year, you would need $2,000,000 ($80,000 x 25 = $2,000,000).
The 4% rule is a starting point, not a guarantee. It assumes a balanced portfolio of stocks and bonds and a 30-year retirement. If you retire early or expect to live longer than 30 years, you may need to withdraw less.
THE 25X RULE
The 25X rule is another common guideline. It is essentially the same as the 4% rule. It suggests that you need 25 times your annual retirement expenses saved. For example, if you need $50,000 per year in retirement, you need $1,250,000 saved.
FACTORS THAT AFFECT YOUR RETIREMENT NUMBER
Several factors can affect how much you need for retirement. Your health is a significant factor. Healthcare costs are one of the largest expenses in retirement. According to estimates, the average couple retiring at age 65 will need $300,000 or more for healthcare costs in retirement. Your housing situation matters. Do you own your home outright, or will you still have a mortgage? Your lifestyle choices are important. Travel, hobbies, and dining out all add to your expenses. Your location affects costs. Living in an expensive city requires more savings than living in a lower-cost area. Your tax situation matters. Retirement income from traditional IRAs and 401(k)s is taxable. Your family situation is a factor. Do you need to support children or aging parents?
HOW TO CALCULATE YOUR RETIREMENT NUMBER
Calculating your retirement number involves several steps. First, estimate your annual retirement expenses. Include housing, healthcare, food, transportation, insurance, and entertainment. Second, subtract any expected retirement income, such as Social Security or pension benefits. Third, apply the 4% or 25X rule to determine your target savings amount.
For example, if your estimated annual retirement expenses are $70,000 and you expect $20,000 per year from Social Security, you need to cover $50,000 per year from your savings. Using the 4% rule, you need $1,250,000 saved ($50,000 x 25 = $1,250,000).
HOW TO REACH YOUR RETIREMENT NUMBER
Reaching your retirement number requires a combination of saving, investing, and planning. The earlier you start, the less you need to save each month. A 25-year-old who starts saving $500 per month and earns an 8% annual return will have approximately $1.5 million by age 65. A 35-year-old would need to save over $1,100 per month to reach the same goal.
Maximizing tax-advantaged accounts is essential. Contribute to your 401(k) and IRA every year. The 2026 contribution limits for 401(k) plans are $23,000 plus a $7,500 catch-up contribution for those over 50. IRA contribution limits are $7,000 plus a $1,000 catch-up contribution for those over 50.
Investing for growth is important. While bonds provide stability, stocks are needed for long-term growth. A 60/40 portfolio (60% stocks, 40% bonds) is a common allocation for retirement investors. However, younger investors may want a higher stock allocation. Older investors may want a more conservative allocation.
WHAT IF YOU ARE BEHIND?
If you are behind on your retirement savings, do not panic. There are steps you can take to catch up. Increase your savings rate. Even a small increase can make a difference over time. If you are over 50, take advantage of catch-up contributions to your 401(k) and IRA. Delay retirement. Working a few extra years can significantly increase your savings and reduce the number of years your savings need to last. Consider part-time work in retirement to supplement your income. Reduce expenses. Downsizing your home or relocating to a lower-cost area can reduce your retirement expenses. Maximize Social Security benefits. Delaying Social Security beyond your full retirement age increases your benefits.
SOCIAL SECURITY: HOW IT WORKS
Social Security is a key source of retirement income for most Americans. Understanding how it works can help you maximize your benefits. Your benefit is based on your highest 35 years of earnings. The full retirement age is 66 to 67, depending on your birth year. You can claim benefits as early as age 62, but your benefits will be permanently reduced. You can delay benefits past your full retirement age, and your benefits will increase by about 8% per year until age 70. Spousal benefits are also available.
WHEN TO START TAKING SOCIAL SECURITY
Deciding when to start taking Social Security is an important decision. Claiming early provides income sooner, but at a reduced rate. If you claim at 62, your benefits are reduced by about 30% compared to claiming at full retirement age. Delaying benefits provides higher monthly payments for life. If you delay until age 70, your benefits increase by about 8% per year after full retirement age. The break-even age is typically around 78 to 80. If you expect to live longer than this, delaying benefits makes sense.
HEALTHCARE IN RETIREMENT
Healthcare is one of the largest expenses in retirement. Medicare is available starting at age 65, but it does not cover everything. Medicare Part A covers hospital care and is typically free. Medicare Part B covers doctor visits and outpatient care and has a monthly premium. Medicare Part D covers prescription drugs. Medigap or Medicare Advantage plans can help cover costs not covered by Medicare. Long-term care is another consideration. Medicare does not cover long-term care. Long-term care insurance can help cover these costs.
COMMON MISTAKES TO AVOID
Avoid these common retirement planning mistakes. Mistake 1: Not starting early enough. Every year you delay costs you thousands in future wealth. Mistake 2: Not contributing enough to get the employer match. This is free money you are leaving on the table. Mistake 3: Not diversifying your retirement portfolio. A diversified portfolio reduces risk. Mistake 4: Ignoring fees. High fees eat into your retirement savings. Mistake 5: Withdrawing money early. Early withdrawals from retirement accounts come with penalties and taxes. Mistake 6: Not planning for healthcare costs. Healthcare is one of the largest retirement expenses. Mistake 7: Claiming Social Security too early. Claiming early permanently reduces your benefits.
THE IMPORTANCE OF STARTING EARLY
Starting early is the most important factor in retirement planning. Even small contributions can grow significantly over time. A 25-year-old who invests $200 per month until age 65 will have approximately $600,000 at retirement, assuming an 8% return. A 35-year-old who does the same will have approximately $260,000. A 45-year-old who does the same will have approximately $100,000. The difference between starting at 25 and starting at 45 is half a million dollars.
CONCLUSION
Retirement planning is essential for a secure financial future. The key is to start early, save consistently, and invest wisely. By calculating your retirement number, maximizing tax-advantaged accounts, and avoiding common mistakes, you can build the retirement you deserve. The journey to a comfortable retirement starts today. Take the first step and begin planning for your future.
About the Author: The Financial Education Team is dedicated to helping individuals build strong financial foundations through clear, actionable guidance on credit, saving, and wealth-building.
Disclaimer: This article is for informational purposes only and should not be considered financial or investment advice. Always conduct your own research or consult a qualified financial advisor before making investment decisions.